

Debbie Rewards
by Debbie Inc.
4.9
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.9
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
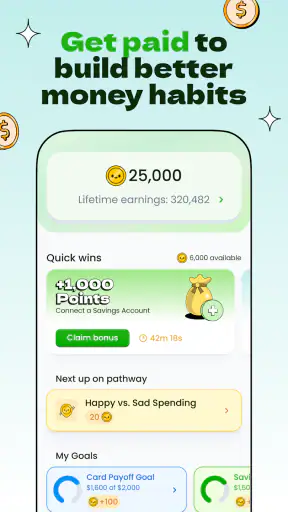
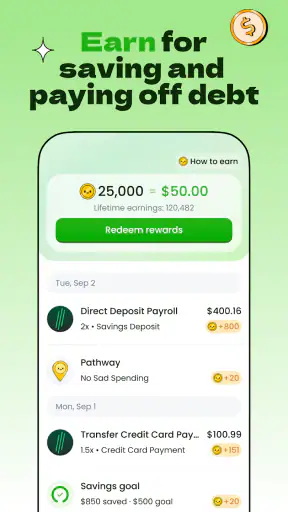
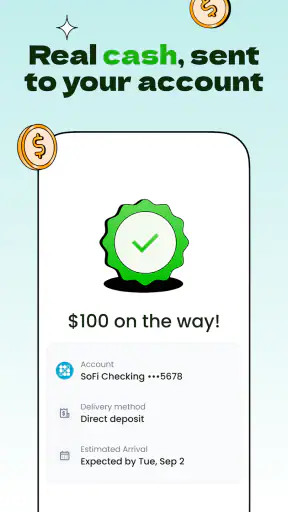
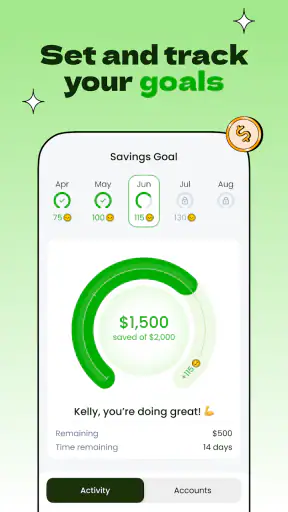
 Analysis by Getfullapps
I approached Debbie Rewards as a practical finance app rather than a simple coupon tool. Its promise is easy to understand: help you pay off debt, save money, and earn rewards. What matters in daily use, though, is whether the routine feels clear enough to maintain. My experience is that the app makes the most sense for people who want a small, repeatable money habit, not for someone looking for a complete replacement for a bank, budgeting platform, or debt counselor.
That distinction is important before installing it. A rewards-focused finance app can be useful when it gives you a reason to return and connect everyday spending with a larger goal. It can also become frustrating if you expect every financial task to happen in one place. Debbie Rewards, developed by Debbie Inc., sits in that middle ground. It is free, aimed at Everyone, and available for Android users running version 7.0 or later. I found its appeal strongest when I treated it as one focused part of a broader money system.
Getting past the points where users usually get stuck
The first difficulty with an app like this is not necessarily a technical error. It is usually an unclear expectation. The short store description, “Debbie Rewards,” does not explain the full experience by itself, while the longer summary points toward paying off, saving, and earning. Those are related goals, but they are not identical workflows. Someone installing it to reduce debt may judge it differently from someone mainly interested in rewards or saving prompts.
I recommend deciding what you want from the app before beginning. If your priority is debt repayment, keep the balance, due dates, and payment method you already use nearby. If your priority is saving, choose one specific purpose rather than trying to organize every financial goal at once. This simple preparation prevents the app from feeling confusing when the real issue is that the user has not chosen a clear starting point.
Another common sticking point is the difference between seeing a reward and understanding how it fits into your finances. A reward is not automatically the same as cash immediately available for a bill. I would read each screen carefully and avoid making a payment decision based only on a headline amount. The useful question is: what action does this reward support, and what step must I complete before it becomes useful to me?
The best way to use Debbie Rewards is to connect it to one existing money habit. For example, I might check it after reviewing a weekly spending total, then decide whether the next action is saving, paying down a balance, or simply learning which opportunity is relevant. That approach is more reliable than opening the app repeatedly without a plan.
What to check before creating a routine
Before relying on the app, I would confirm that the installation is current and that the device meets the minimum operating-system requirement. The current version is 2.6.36, and the Android requirement is 7.0 or later. Those details matter because an older phone can create symptoms that look like an app problem: slow screens, failed updates, or unexpected closing. Updating the operating system and the app itself is a sensible first step before troubleshooting anything more complicated.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I would also make sure the phone has a stable internet connection during initial setup and when completing any action that depends on current account or reward information. A weak connection can leave a screen half-loaded or make a completed action appear unfinished. Rather than tapping repeatedly, wait, return to the relevant screen once, and check whether the status changed. Repeated taps can create uncertainty about what actually happened.
Account details deserve the same care as the technical setup. Use the email address or sign-in method you intend to keep using, and store any recovery information safely. If the app asks you to verify something, finish that process before exploring every section. Skipping setup steps may make the app appear empty or limit what you can do, even though the installation itself is working normally.
Privacy is another practical checkpoint. Finance apps deserve a slower installation than a casual game. I would review what the app requests, why a particular connection might be useful, and whether I am comfortable granting it. If I do not understand a permission or account connection, I would pause rather than approving it automatically. This is not a criticism unique to Debbie Rewards; it is simply the right standard whenever an app touches financial behavior.
A setup routine that reduces confusion
My preferred setup order is deliberately simple. First, install the latest available version on a compatible device. Next, complete the account and verification steps without switching between several devices. Then, identify the one goal that matters most this month. Finally, spend a few minutes looking at the available actions before deciding which ones deserve regular attention.
This order avoids a subtle mistake: trying to optimize rewards before understanding the basic flow. If the app presents several ways to save, earn, or work toward payoff, choosing everything at once can make progress difficult to judge. I would start with the option that requires the least change to my current routine, then evaluate whether the result is genuinely useful.
A useful test is to ask whether I can explain the next action in one sentence. “I will review this after my weekly budget check” is clear. “I will keep checking until I find something valuable” is not a routine; it is an invitation to waste time. This small test helps separate a helpful financial tool from another notification competing for attention.
Recovering when a workflow does not complete
When something appears stuck, I would avoid assuming that the underlying financial action failed. First, I would check the connection, close and reopen the app, and look for the current status rather than starting over immediately. If the screen still looks unchanged, I would restart the phone and confirm that the app is updated. These are ordinary steps, but they solve many problems caused by temporary loading or an interrupted session.
If the issue involves a bank, card, payment service, or another outside account, I would check that service separately. A delayed balance or missing confirmation may originate outside Debbie Rewards. Looking at the external account can prevent duplicate actions. For example, if I tried to complete something and the app did not refresh, I would verify whether the transaction or update already appeared elsewhere before repeating it.
I would also record the useful details before contacting support: the device model, operating-system version, app version, the screen where the problem appeared, and the approximate time. A short description such as “the confirmation did not refresh after reconnecting” is more helpful than “the app is broken.” I would never include passwords, full card numbers, or other sensitive credentials in a support message.
There is a difference between a temporary display issue and a failed financial action. If the app shows an incomplete status, I would treat the action as unconfirmed until I can verify it through the relevant account or service. That cautious habit is especially important for debt payments. Convenience should not replace checking whether money actually moved.
When the app may not be the real cause
Finance workflows involve several moving parts, so not every delay belongs to the app. A bank may be processing an update, a card may be restricted, a connection may have expired, or a device may be blocking background activity. The practical response is to isolate the problem instead of reinstalling immediately. Check the phone connection, the outside account, and the app status one at a time.
Reinstalling can be useful as a last resort, but I would not make it the first response. Before removing the app, confirm that I know the correct sign-in details and that any important information is safely associated with the account. Otherwise, a troubleshooting step can create a separate recovery problem.
Notifications can cause similar confusion. If I stop receiving reminders, I would check both the app’s notification settings and the phone’s system settings. Battery-saving controls can also delay alerts on some devices. At the same time, I would not depend on a notification as the only reminder for a debt due date. A calendar reminder or existing banking alert is a safer backup because the consequences of missing a payment are more serious than missing an in-app prompt.
This is also where expectations matter. Debbie Rewards can support a financial routine, but it should not be treated as proof that a balance is correct, a payment has cleared, or a debt plan is mathematically optimal. For those questions, the original lender, bank, or a qualified financial professional remains the better authority.
Everyday uses that make the app more worthwhile
One realistic use case is a person who has a regular debt payment and wants extra motivation to keep the goal visible. Instead of opening the app whenever they are bored, they could review it immediately after their normal weekly money check. They would note any relevant reward or saving opportunity, compare it with the month’s priority, and then return to the lender or bank for confirmation of actual payments. The app becomes a prompt within a process, not the entire process.
A second use case is someone building a modest saving habit while still working on debt. Here, the trade-off is important. Sending every available dollar toward debt may be sensible in one situation, while keeping a small emergency buffer may be more practical in another. Debbie Rewards can encourage action, but it cannot decide that trade-off responsibly without knowing the person’s income, interest rates, bills, and financial safety net. I would use it to reinforce a decision I have already made, not to outsource that decision.
A less obvious benefit is behavioral rather than numerical. Rewards can make an otherwise repetitive task feel more visible. That can help a user who understands budgeting but struggles to return to it consistently. The limitation is that motivation fades if the workflow takes too long or the reward does not feel connected to a meaningful goal. I would therefore judge the app by whether it helps me act, not by how often I open it.
There is also a useful boundary for families and shared finances. Because the age rating is Everyone, the app is broadly accessible, but that does not mean a child should manage financial connections independently. An adult should decide what accounts are appropriate, explain the purpose of the app, and keep control of sensitive credentials. Accessibility is not the same thing as suitability for every financial responsibility.
How it compares with ordinary alternatives
The usual alternative is a bank’s own app. A banking app is generally the place to confirm balances, view transactions, and verify payments. Debbie Rewards has a different role: it is more focused on encouraging payoff, saving, and earning behavior. I would use the bank for authoritative account information and this app for motivation or opportunities, rather than expecting either one to replace the other.
A spreadsheet or notebook is another alternative. Those tools offer more control and can be tailored to complex household budgets, irregular income, or detailed debt calculations. They require more manual work, however, and they do not necessarily provide the same reward-oriented experience. If I need precise forecasting, a spreadsheet is likely better. If I need a lighter prompt to keep a goal active, Debbie Rewards may be easier to revisit.
Dedicated budgeting software can be stronger for category tracking and long-term planning. The trade-off is setup effort and the possibility of managing more information than I actually need. Debbie Rewards is a better fit when the main challenge is taking a few focused actions around saving or payoff. It is not the right choice for someone who wants a full household ledger, investment dashboard, or detailed financial plan.
That comparison also explains who should skip it. I would look elsewhere if I needed guaranteed payment scheduling, advanced debt calculations, extensive reporting, or a single dashboard for every account. I would also skip it if I already have a disciplined system that works and rewards would only add another distraction. More tools do not automatically produce better financial decisions.
My practical verdict after using it
Debbie Rewards works best when I give it a narrow job: help me stay engaged with saving, earning, or paying off debt while I keep official account checks in the appropriate banking or lender app. Its free price lowers the barrier to trying it, and its 4.9 average from around 14 thousand ratings suggests that many users find the experience worthwhile. It has also passed the threshold of over 100 thousand installs, which gives it a meaningful user base without changing the need to evaluate whether its workflow suits me.
The strongest reason to try it is behavioral. If I need a gentle reason to return to a financial goal, the combination of payoff, saving, and rewards is more inviting than a blank spreadsheet. The strongest reason not to rely on it alone is scope. It should not replace transaction verification, payment records, careful debt planning, or sensible privacy habits.
My advice is to install it with one goal, test the routine for a short period, and keep a separate authoritative record for important payments. If the app makes that routine easier, it earns a place in my financial toolkit. If it creates more checking than action, I would remove it without hesitation. For me, the practical value is not in treating Debbie Rewards as a complete financial command center, but in using it as a focused nudge toward better money habits.
Pros
- Simple way to earn points from everyday purchases
- Rewards can make regular shopping feel more worthwhile
- Useful for users who already shop with participating brands
- Clear reward-focused design is easy for beginners to understand
- May offer exclusive deals or bonuses unavailable elsewhere
Cons
- Rewards may be limited to specific stores, products, or locations
- Points can take time to accumulate before becoming useful
- Some offers may include expiration dates or redemption restrictions
- Requires sharing personal and purchase information to use fully
- App value depends heavily on the availability of participating retailers
FAQs for Debbie Rewards
What is Debbie Rewards and how does it work?
Debbie Rewards is a rewards-focused mobile app designed to help users earn benefits through eligible activities, offers, or purchases available inside the platform. After creating an account, you can browse the opportunities shown in the app, review their requirements, and complete them as instructed. Rewards, points, or cashback may depend on the offer, location, account status, and verification rules.
Is Debbie Rewards free to download and use?
The app is generally available to download without an upfront purchase, but users should still review the conditions associated with individual offers before participating. Some promotions may require a qualifying purchase, subscription, referral, or other action. Standard mobile data charges may also apply, and the availability of rewards can vary depending on your country, device, and current promotional terms.
How can I redeem rewards in Debbie Rewards?
Redemption normally depends on the type of reward you have earned and whether your account has met all eligibility requirements. Open the rewards or wallet section, check the minimum balance and any expiration information, then follow the provided instructions. Some rewards may require identity, payment, or account verification, so processing times and available redemption methods can differ.
Is Debbie Rewards safe and what information does it require?
Before registering, users should review Debbie Rewards’ privacy policy, terms of service, and permissions requested by the app. Rewards platforms may collect information such as an email address, account details, device data, activity information, or transaction records to operate and verify offers. Downloading from an official app store and avoiding suspicious links can help reduce security risks.
Why might an offer or reward not appear in Debbie Rewards?
Offers are often personalized and may change according to location, device compatibility, account history, availability, and campaign limits. A reward may also be delayed if an action has not been tracked correctly, if the requirements were not completed exactly, or if verification is still pending. Check the offer terms, keep confirmation records, and contact in-app support when necessary.

Debbie Rewards
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@joindebbie.com, visit https://www.joindebbie.com, or review their https://www.joindebbie.com/privacy-policy.










